AI in banking in India has transitioned from a theoretical competitive advantage into an absolute operational necessity, particularly within the heavily scrutinized domain of debt collections in IIndia. For banking leaders navigating the complex regulatory and operational landscape across financial hubs, reliance on brute-force, call-center-heavy recovery models is rapidly becoming a liability. Modern collections demand hyper-personalized, compliant, and cost-efficient strategies that protect both margins and institutional reputation.
The Escalating Costs and Risks of Legacy Recovery
The RBI’s zero-tolerance policy regarding borrower harassment, strict calling-hour limitations, and the enforcement of the Digital Personal Data Protection Act (DPDPA) mean that a single non-compliant action by a stressed human recovery agent can result in massive institutional penalties.
Simultaneously, banks face high attrition rates in their collections call centers, meaning they are constantly relying on newly trained, error-prone staff to handle sensitive financial negotiations. The problem is a paradox: institutions need to increase their contact rates to combat rising retail defaults, but scaling human operations exponentially increases the risk of regulatory violations.
The 3 Core Pillars of Unified Intelligent Debt Collection in India
To achieve efficient debt collection, leading institutions are harnessing the use of AI in banking in India across three critical collection touchpoints:

Predictive AI & Propensity Scoring
Rather than treating all delinquent accounts identically, advanced predictive engines ingest thousands of transactional, behavioral, and bureau signals. These algorithms assign precise propensity-to-pay scores, allowing institutions to micro-segment their portfolios. High-propensity borrowers receive low-friction digital nudges, while high-risk accounts are flagged for immediate strategic intervention—slashing unnecessary outreach expenses by up to 40%.
Multilingual Voicebots with Compliance-as-Code
NLP-driven voicebots handle early-stage delinquencies at a fraction of human cost. Operating strictly within RBI-mandated timeframes, these voicebots conduct empathetic, multi-lingual dialogues in regional Indian languages. They deliver uncompromised script compliance, zero fatigue, and complete auditability for regulatory reporting.
Frictionless Digital Self-Service Portals
Borrower psychology shows that many defaults stem from temporary liquidity mismatches paired with an aversion to confrontational phone calls. Secure, one-click self-service portals delivered via SMS or WhatsApp allow borrowers to view outstanding balances, choose structured settlement plans, and execute payments instantly on their own terms. This digital autonomy dramatically improves promise-to-pay (PTP) conversion rates while elevating the overall customer experience.
Conclusion: Secure Your Recovery Ecosystem with mCollect
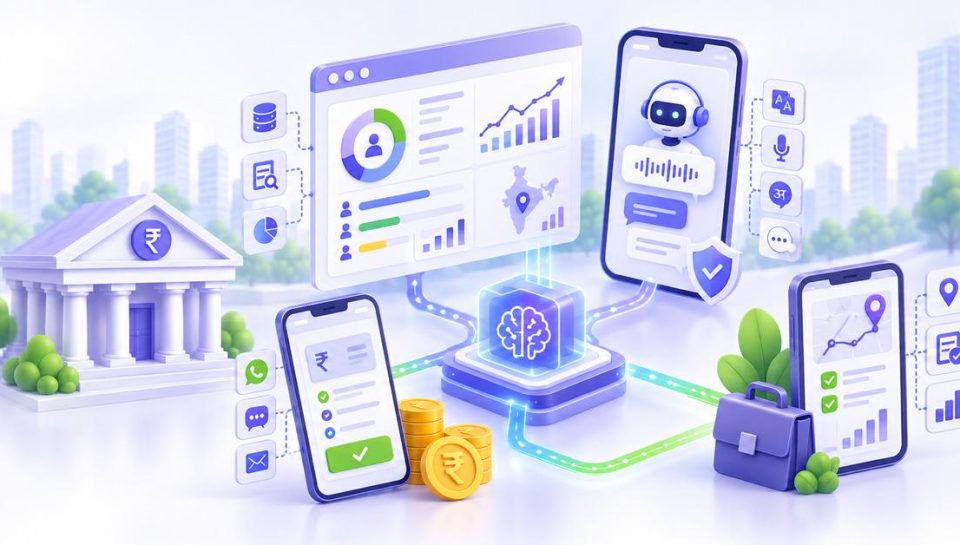
This is precisely why forward-thinking enterprise leaders are adopting mCollect— Unified AI Debt Collection. One of the best phygital debt resolution and debt collections platform in India, mCollect intelligently injects predictive propensity scoring, regional conversational AI voicebot, and intuitive self-service portal into a unified workflow.
Crucially, mCollect bridges the digital-to-physical gap. When digital channels hit a limit, the debt collection platform seamlessly hands over contextualized intelligence to field recovery teams via smart mobile applications—ensuring end-to-end tracking, complete field visibility, and strict DPDPA, TRAI & RBI compliance across every lifecycle stage.