The Evolution of Gold Loans in Retail Credit
Gold loans are experiencing an unprecedented credit surge across the Indian BFSI landscape, fundamentally altering the asset composition of major financial institutions.
Recent macroeconomic data, reinforced by updates from the Reserve Bank of India (RBI), highlights a massive double-digit year-on-year growth in lending against precious metals throughout 2026. Historically, this segment was predominantly controlled by specialized Non-Banking Financial Companies (NBFCs) with deep rural penetration and agile disbursement cycles.
However, the market is currently witnessing a forceful entry by large private sector banks.
These top-tier institutions are no longer content with the periphery; they are actively targeting the urban, higher-ticket demographic.
Why Large Private Banks Are Pushing for Gold loan Automation

The strategic rationale driving large private banks to escalate their presence in gold loans is fundamentally rooted in capital efficiency and superior risk-adjusted returns. According to a comprehensive Motilal Oswal Financial Services report highlighted recently in ETBFSI, private banks are accelerating their strategic investments to secure incremental market share, particularly focusing on higher-ticket, urban borrower profiles.
Historically, mainstream commercial banks hesitated to aggressively pursue this vertical due to the formidable operational expenditures required. Establishing a profitable portfolio demanded heavy upfront investments in highly secure vaulting facilities, networks of trained assayers, and specialized branch infrastructures. However, the industry dynamics have profoundly evolved. The magnetic pull of minimal credit costs, shorter payback periods, and soaring customer acceptance for pledging physical assets has overshadowed those initial operational barriers.
Leading institutions are already demonstrating explosive portfolio growth. The ETBFSI report notes that major entities like HDFC Bank witnessed their gold loans portfolios rise 34% year-on-year to ₹237 billion in FY26. Similarly, IDFC First Bank’s book surged an impressive 79% to ₹39 billion, while Axis Bank experienced a 23% increase to ₹133 billion.
While entrenched NBFCs like Bajaj Finance—projecting a ₹300 billion book by March 2027—maintain a fortress in rural segments due to their established agility, banks are forcefully leveraging their lower cost of capital to disrupt the urban markets. With the overall industry projected to expand at a 28% compound annual growth rate (CAGR) from FY26 to FY28, the competitive landscape is intensifying rapidly.
Yet, for Legal and Debt Recovery leaders, processing massive daily volumes of gold loans narrows the margin for error. Inaccurate collateral valuation or flawed KYC documentation during rapid origination can trigger catastrophic legal roadblocks during the auction or debt recovery phase.
Securing Gold loan Origination and Debt Recovery
To mitigate these inherent operational and legal risks, BFSI institutions require an enterprise architecture that seamlessly bridges rapid origination with an airtight compliance framework. This is where Kanak by Mobicule, an industry-leading Gold Loan Origination System (LOS), emerges as the definitive solution for scaling portfolios securely.
Engineered specifically to resolve the complex pain points of BFSI C-suite leaders, Kanak standardizes and accelerates every phase of the lending lifecycle.
However, its most critical value proposition lies in its robust risk management and compliance capabilities.
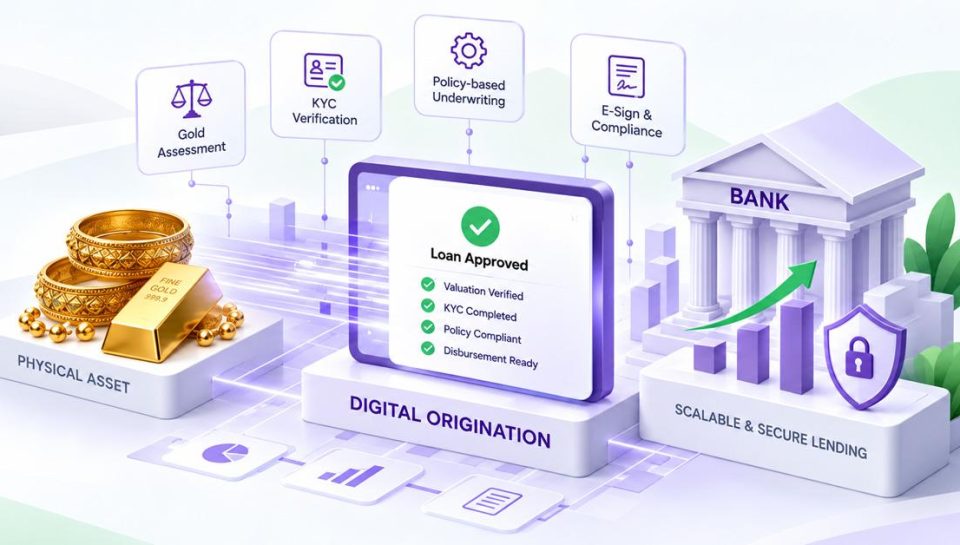
From a legal defense standpoint, Kanak provides a fully compliant digital e-sign architecture that ensures all gold loans agreements are instantly executed and legally binding under Indian regulatory frameworks. Should a borrower transition into delinquency, Kanak seamlessly channels verified collateral data into Mobicule’s comprehensive Debt Monitoring and Recovery platforms, empowering legal departments to initiate swift, compliant auctioning and recovery proceedings.
Kanak features a highly specialized Gold Assessment module, providing a professional assayer interface for real-time authentication, weight verification, and exact valuation. By enforcing a standardized digital record of the physical collateral, the platform proactively protects collections teams from the systemic risk of under-collateralized gold loans defaults.
Furthermore, Kanak’s intelligent underwriting engine enforces strict policy-based approvals. The platform is deeply integrated with leading KYC APIs—such as Netrascan—ensuring comprehensive deduplication checks, instant identity validation, and absolute adherence to RBI regulations.
Conclusion: Future-Proofing Gold Loans Portfolios
Progressive BFSI decision-makers must recognize that sustainable growth demands flawless digital execution. Equipping origination, legal, and collections departments with a specialized, enterprise-grade platform is no longer optional—it is a critical mandate. By adopting state-of-the-art origination infrastructure, banking leaders can ensure unparalleled speed, absolute regulatory compliance, and a proactive defense against non-performing assets.
It is time to transform institutional lending capabilities.
Explore how Mobicule’s Kanak can completely revolutionize your secured lending ecosystem. Request a comprehensive demonstration today, and establish your institution as the undisputed leader in the rapidly expanding market for gold loans