Due to lack of data-driven debt collection approach, collection heads across banks, NBFCs, Housing Finance Companies (HFCs), and Microfinance Institutions (MFIs) face a persistent operational bottleneck: determining the exact moment an overdue account should transition from internal digital outreach to legal escalation.
Historically, recovery teams have relied on subjective judgment, manual follow-ups, and static Days Past Due (DPD) thresholds. However, holding onto delinquent accounts too long inflates the Cost of Recovery (CoR) and drastically decreases net recovery yields.
To optimize retail debt recovery across both secured and unsecured portfolios, modern financial institutions are abandoning manual guesswork. Implementing a data-driven debt collection framework allows lenders to establish objective, automated triggers for legal escalation, keeping operational costs low while maintaining strict regulatory compliance.
The Cost of Delay in the 60–90 DPD Bucket
In unsecured lending—such as personal loans, credit cards, and Buy Now Pay Later (BNPL) products—the window for cost-effective recovery is narrow. As accounts linger in the crucial 60 to 90 DPD bucket, repayment probability drops exponentially while internal operational expenses rise.
When internal tele-calling teams repeatedly engage non-responsive or high-risk borrowers, they exhaust Full-Time Equivalent (FTE) resources without yield. Research from recent Reserve Bank of India (RBI) financial stability reviews and banking industry benchmarks highlights that recovery yields for unsecured debts drop by up to 40% once an account crosses the 90 DPD threshold without formal legal intervention.
Delaying legal notices or arbitration in the hope of an informal resolution creates unnecessary friction. Instead, applying data-driven debt collection parameters ensures that non-performing accounts are flagged for formal recovery mechanisms immediately when engagement stalls.
Behavioral Scoring Over Gut Feeling in Debt Resolution
Relying on a collector’s “gut feeling” introduces human bias and inefficiency into loan recovery operations. Modern recovery strategies require behavioral scoring models that evaluate real-time borrower intent, payment histories, and interaction data to determine next steps.
By transitioning from manual outreach to an automated debt collection platform, algorithms analyze hundreds of borrower attributes:
- Intent Signals: Has the borrower opened WhatsApp payment links, answered voicebot calls, or requested restructuring terms?
- Financial Risk Indicators: Are there multiple cheque bounces (Section 138 triggers) or recurring ECS/NACH failures across other credit accounts?
- Asset Depreciation Risk: For secured loans (auto or home loans), is the asset losing value while the borrower avoids contact?
If behavioral analytics reveal a clear pattern of refusal or high default risk, the system automatically redirects the account away from field collection and straight to the legal desk. This prevents FTE waste, mitigates compliance risks linked to excessive calling, and accelerates court-ready preparations.
Automated Legal Triggers via mCollect
Mobicule’s mCollect delivers a full-stack, phygital recovery ecosystem built specifically for enterprise BFSI and Telecom lenders. By unifying AI-driven digital nudges, field agent tracking, and legal notice automation onto a single intelligent platform, mCollect streamlines end-to-end recovery workflows for secured and unsecured loans alike.
How mCollect Automates the Escalation Lifecycle:
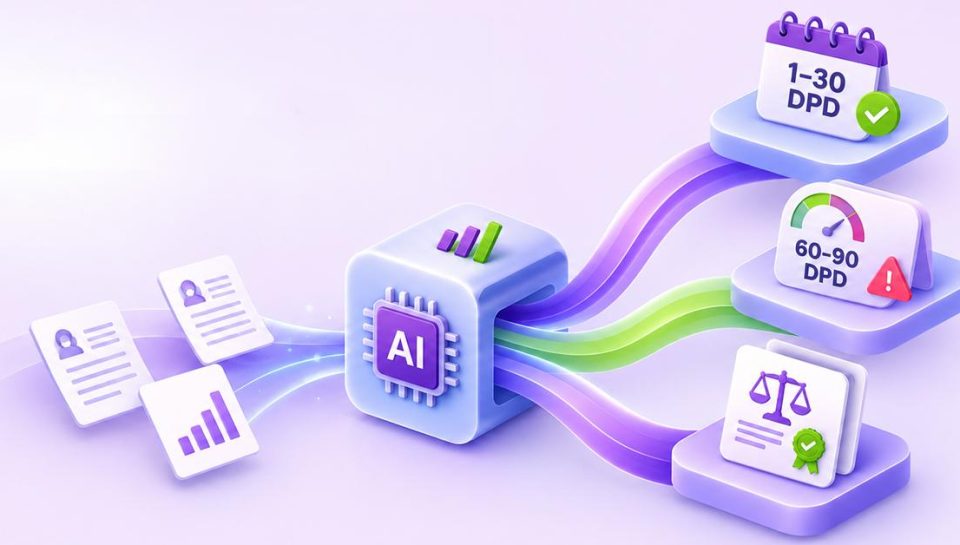
Seamless Legal Notice Generation: mCollect generates legally verified demand notices, conciliation invites, or SARFAESI notices in one click, complete with integrated Speed Post tracking and court-ready proof of delivery.Rule-Based Systems vs. Mobicule’s mCollect
Early-Bucket Self-Resolution: Early-stage delinquencies (1–30 DPD) are handled seamlessly via omnichannel digital dunning—including WhatsApp, Google RCS, IVR, and interactive AI voice bots. This yields high auto-cure rates at a fraction of traditional operational costs.
Algorithmic Risk Flagging: When an account hits pre-configured risk triggers (e.g., zero engagement across 3 digital channels + 60 DPD), mCollect automatically halts manual calls to ensure RBI compliance and queues the file for legal review.
Why Enterprise Lenders Choose mCollect for End-to-End Recovery
To help BFSI decision-makers evaluate technology investments, the comparison table below highlights the operational advantages of mCollect’s end-to-end digital debt collection platform over legacy manual setups:
| Capability / Metric | Legacy / Manual Debt Recovery | mCollect Enterprise Debt Platform |
| Decision-Making | Subjective, collector-dependent decisions | Objective, AI-driven behavioral triggers |
| Early-Bucket Resolution | High FTE cost with manual calling agents | Automated digital cures via WhatsApp, RCS & Voicebots |
| Legal Escalation Speed | 15–30 days manual drafting & posting | Instant one-click notice automation & Speed Post tracking |
| Regulatory Compliance | Risk of agent harassment or non-compliant calls | Enforced RBI Fair Practice compliance with built-in audit trails |
| Portfolio Support | Siloed tools for secured vs. unsecured debts | Unified phygital platform for all retail credit products |
| Overall Cost of Recovery (CoR) | High operational overhead & lingering bad debts | Reduces overall cost-to-collect by up to 80% |
Conclusion
Continuing to rely on manual outreach for accounts that show zero intent to pay inflates operational costs and compromises recovery yields. By embedding data-driven debt collection intelligence into your institution’s recovery framework, you eliminate human bottlenecks, uphold regulatory compliance, and accelerate debt resolution.
Transform your recovery operations with a full-stack digital solution engineered for Indian financial institutions. Explore Mobicule mCollect’s Digital Collection Suite today to schedule an executive demo and optimize your secured and unsecured debt portfolios.