Field debt collection software has become an absolute operational necessity for modern Banks and NBFCs. Despite advancements in digital payments, a massive chunk of recoveries in India—especially across Tier-2, Tier-3 cities, and rural portfolios like commercial heavy duty vehicles, agricultural loans, rural housing loans etc.—still relies on face-to-face interactions and physical cash handling. This traditional approach introduces severe vulnerabilities: cash skimming, delayed banking reconciliation, location spoofing, and compliance breaches.
According to recent 2026 industry insights on unified debt collection, relying on fragmented legacy systems leaves lenders blind to what happens on the ground. If your field agents operate without strict compliance guardrails, your bottom line is actively bleeding. To combat this, leading financial institutions are pivoting toward robust field collection management software designed to digitally track doorstep recoveries, eliminate human error, and secure every transaction.
The Cost of Invisibility: Identifying Pain Points in Manual Field Collection
For CROs and National Collections Heads, the primary anxiety revolves around the “blind spot” between an agent collecting funds at a borrower’s doorstep and those funds officially reflecting in the core banking system (CBS). In legacy models, this gap is where critical leakages occur.
First, there is the risk of location spoofing. Without geo tagged field collection, agents can manipulate visit reports, claiming borrower unavailability without ever stepping foot on the premises. This severely degrades contact ratios and prolongs the delinquency cycle. Secondly, manual receipt books are breeding grounds for fraud. Unscrupulous practices like “teeming and lading”—where cash collected from one borrower is temporarily pocketed and covered by a subsequent borrower’s payment—wreak havoc on ledgers and destroy customer trust.
Furthermore, delayed reconciliation creates an artificial liquidity crunch. When field collection agents wait days to deposit cash and submit paperwork, the CBS remains un-updated. Borrowers who have already paid may receive automated dunning calls, leading to severe customer dissatisfaction and potential regulatory penalties under stringent RBI grievance frameworks. To scale operations sustainably across India’s diverse topography, these manual friction points must be eradicated through capable field debt recovery software.
Steps to Digitize: Automation via Field Debt Collection Software

Eradicating field leakage requires shifting from trust-based operations to system-enforced accountability. Implementing advanced field collection software achieves this through three critical operational steps:
1. Mandating Real-Time Geo-Tagging and Face Verification:
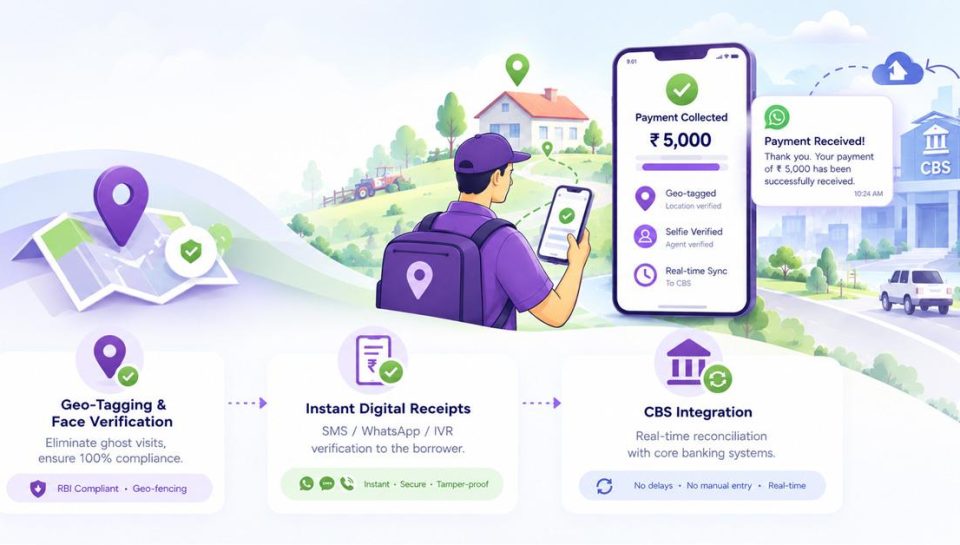
True visibility starts with knowing exactly where your agents are. Modern field collection management software enforces geo-fencing. An agent cannot initiate a case disposition or generate a receipt unless their GPS coordinates match the borrower’s registered address. Coupled with real-time time-stamping and selfie-based check-ins, this ensures 100% RBI geo-tagging compliance and eliminates ghost visits completely.
2. Enabling Instant Digital Receipts and SMS/WhatsApp Verification:
The moment an agent collects a payment—whether via UPI, QR code, or physical cash in an offline mode—the field debt recovery software must instantly generate a secure, untamperable digital receipt. This receipt is immediately sent to the borrower via an SMS, WhatsApp notification, or an IVR confirmation call. By bringing the borrower into the verification loop instantly, the opportunity for cash skimming or receipt alteration drops to zero.
3. Automated Ledger Integration for Core Banking Systems (CBS):
A standalone app is insufficient; it must talk to your central infrastructure. The best field collection software seamlessly integrates with legacy banking systems to automate reconciliation. As soon as connectivity is restored (in offline-first scenarios), the transaction data, geo-tagged evidence, and case disposition sync directly to the CBS. This eliminates manual data entry, prevents reconciliation delays, and ensures your risk monitoring dashboards reflect real-time portfolio health.
Conclusion: Secure Your Recoveries with mCollect Field Debt Collection Software
In the high-stakes environment of BFSI debt recovery, there is no margin for operational leakage. As decision-makers, the mandate is clear: empower your field force with technology that enforces compliance, protects revenue, and respects the borrower’s experience.
This is where Mobicule’s mCollect stands as the industry-leading field debt collection software. Built specifically for the complexities of the Indian market, mCollect transforms every field executive’s smartphone into a secure, offline-first collection terminal. With built-in real-time geo tagged field collection, instant WhatsApp and SMS receipt generation, and flawless CBS integration, it completely eliminates cash leakages.
Do not let manual inefficiencies dictate your NPA metrics. Take control of your last-mile operations with precision and authority. Empower your on-ground teams with an audit-ready, intelligent platform.